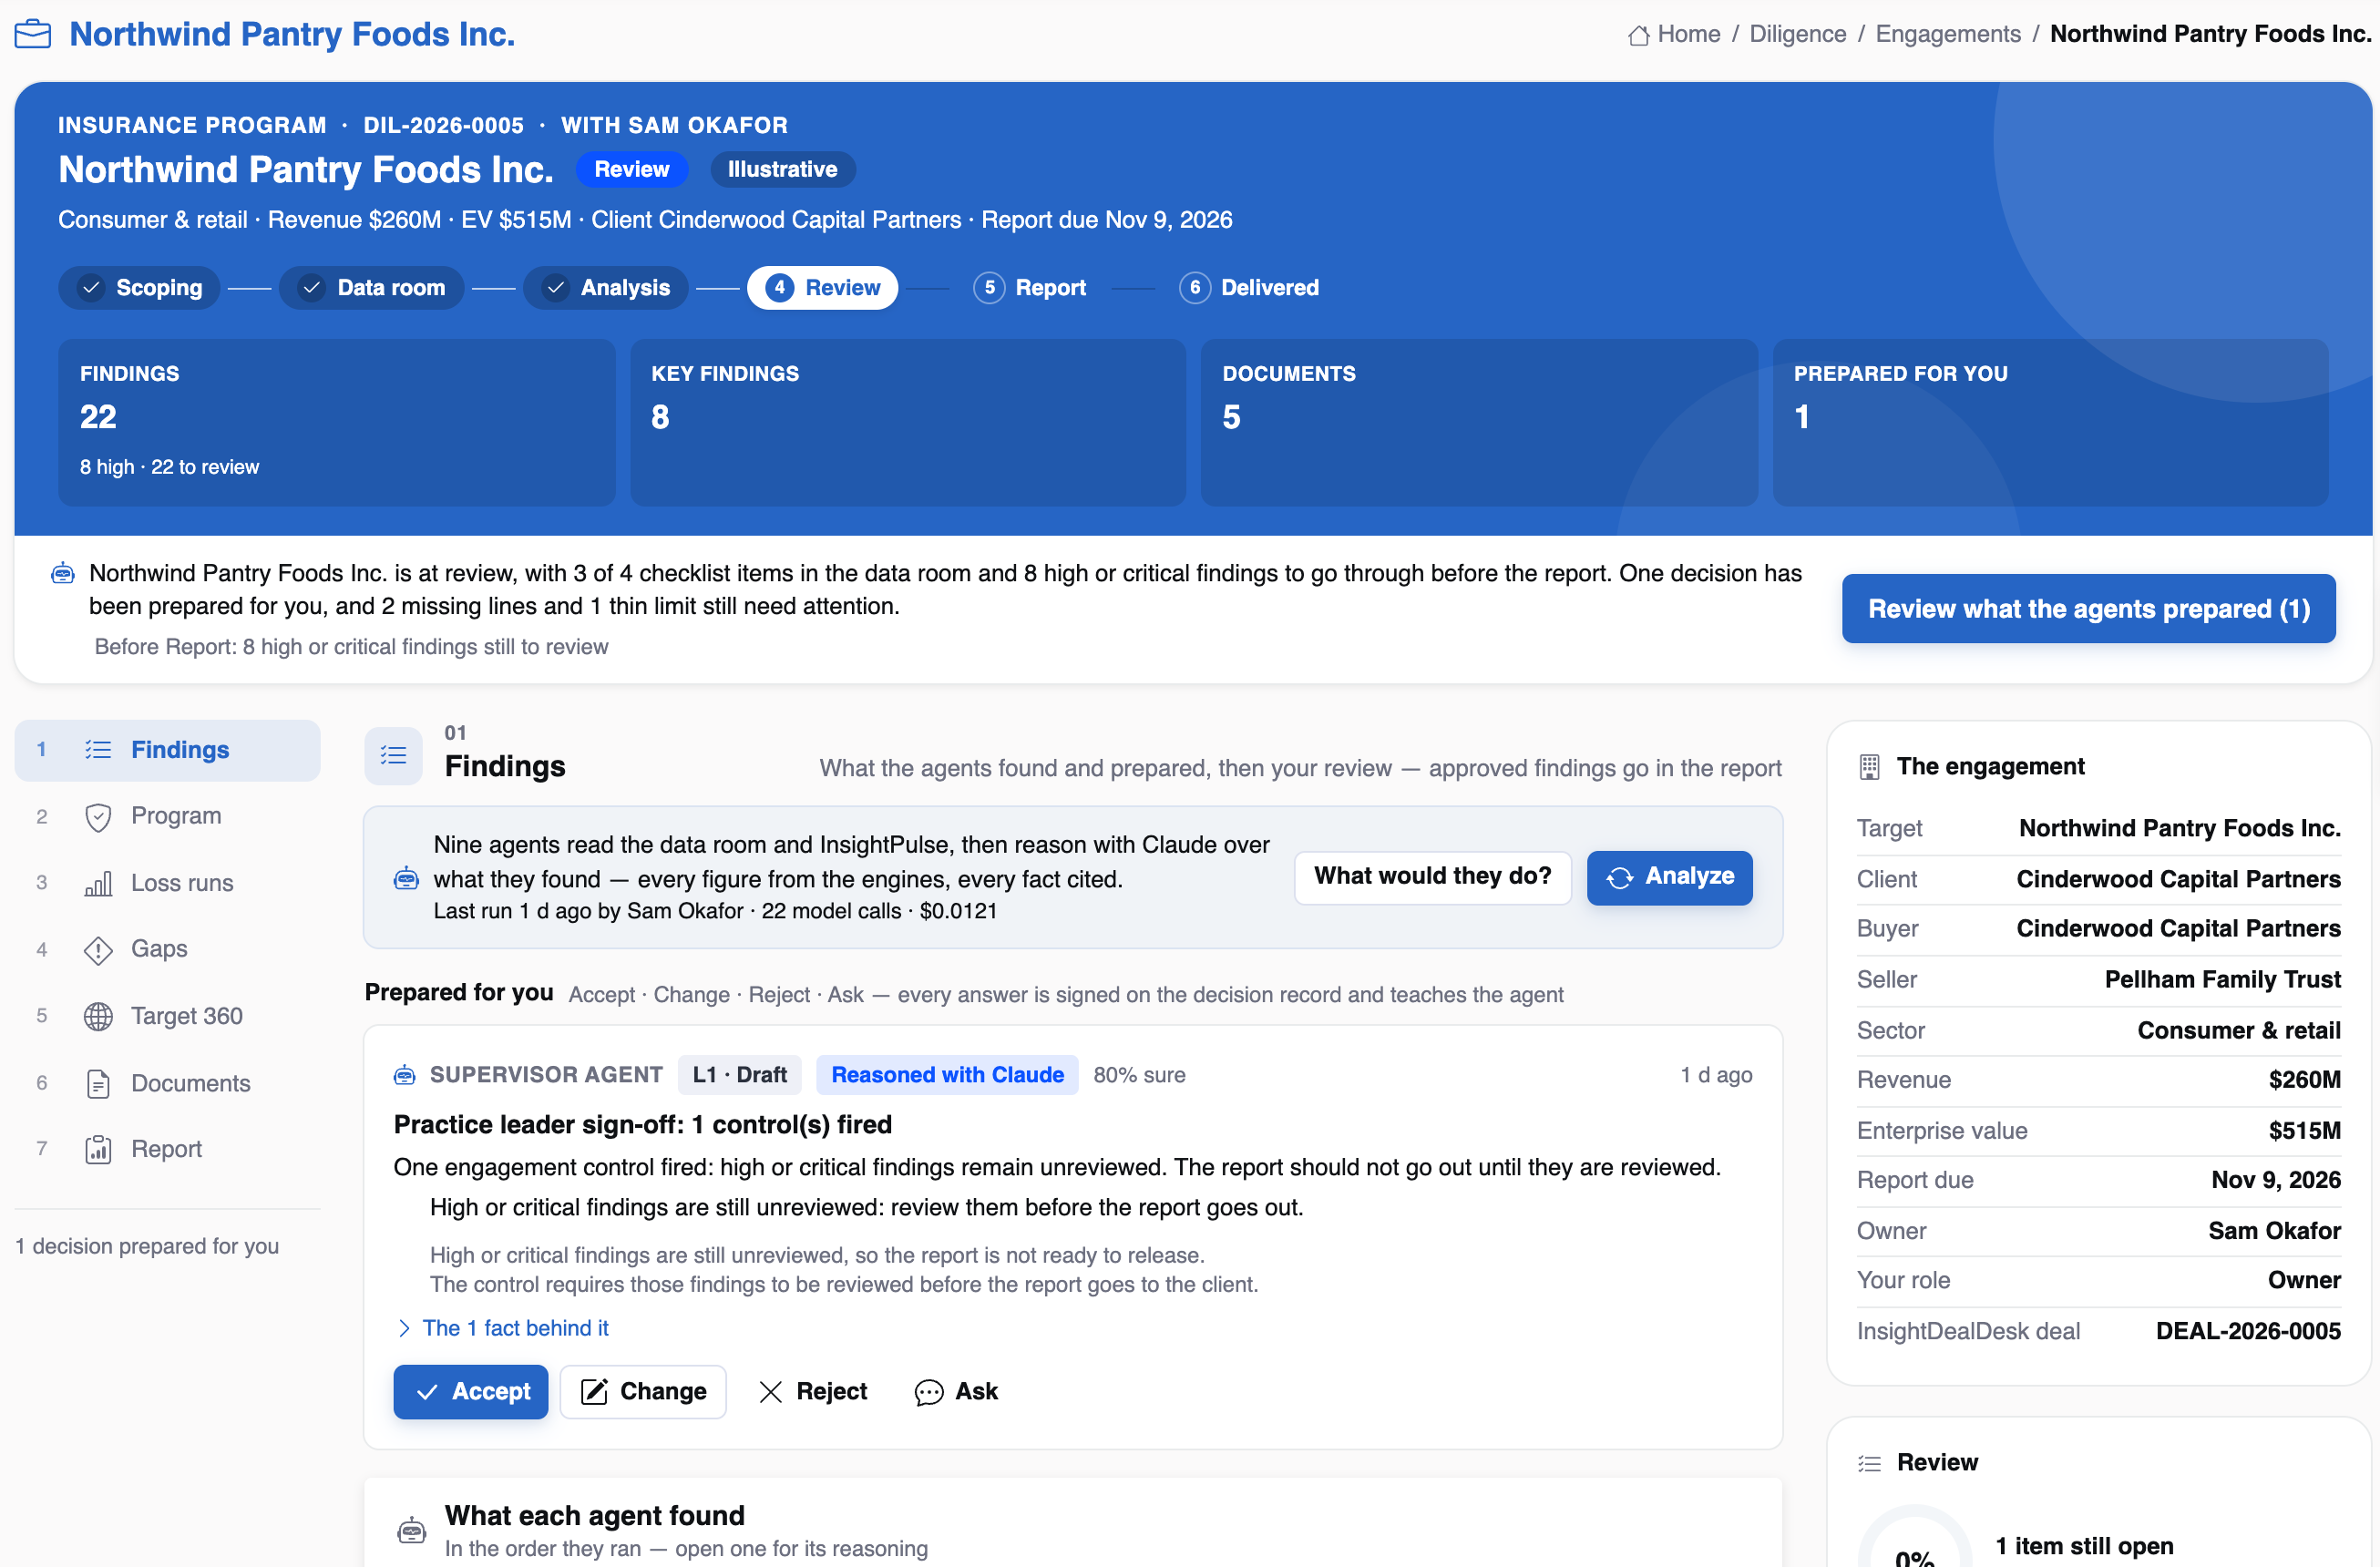
A buyer is acquiring a family-owned snack and pantry food manufacturer. In April it recalled two snack bars for an undeclared allergen. The recall cost $1.1 million so far, and none of it was insured, because the program has no product recall policy. The company also bought a smaller snack maker last year, which still has its own general liability policy. Everything here is illustrative.
| Engagement | Project Harvest — Northwind Pantry Foods Inc. (illustrative), DIL-2026-0005 |
|---|---|
| Deal | Illustrative $515M EV; revenue $260M; 1,120 employees. Buyer Cinderwood Capital Partners, seller a family trust (illustrative) |
| Actors | Deal broker (owner), practice leader, analyst |
| Data room | Schedule of insurance, declarations, loss runs, quality and recall summary |
| Agents involved | All nine; the coverage gap, subsidiary and contingent liability agents carry this one |
| Decisions and authority | Broker reviews; recall cover and the subsidiary go into the buyer’s program at closing |
| Systems touched | InsightPulse (the 2025 acquisition in the hierarchy, recall news), InsightDealDesk (DEAL-2026-0005) |
| Outcome | 22 findings, 8 high: an uninsured recall, no recall or EPL policy, a subsidiary no policy names, and a GL policy expiring weeks after closing |
Three findings that connect
undeclared peanut,
$1.1M cost"] --> N["No product recall policy"] N --> G1["Coverage gap:
recall (benchmark for consumer)"] GF["Golden Furrow Snacks
acquired 2025"] --> S["Not named on
the program"] GF --> E["Own GL policy
expires 2026-12-31"] S --> FIX["Add as named insured
before closing"] E --> FIX G1 --> BUY["Buy recall in the
buyer's program"] style R fill:#fdecec,stroke:#e57373 style FIX fill:#e7f8f1,stroke:#10b981 style BUY fill:#e7f8f1,stroke:#10b981
Step by step
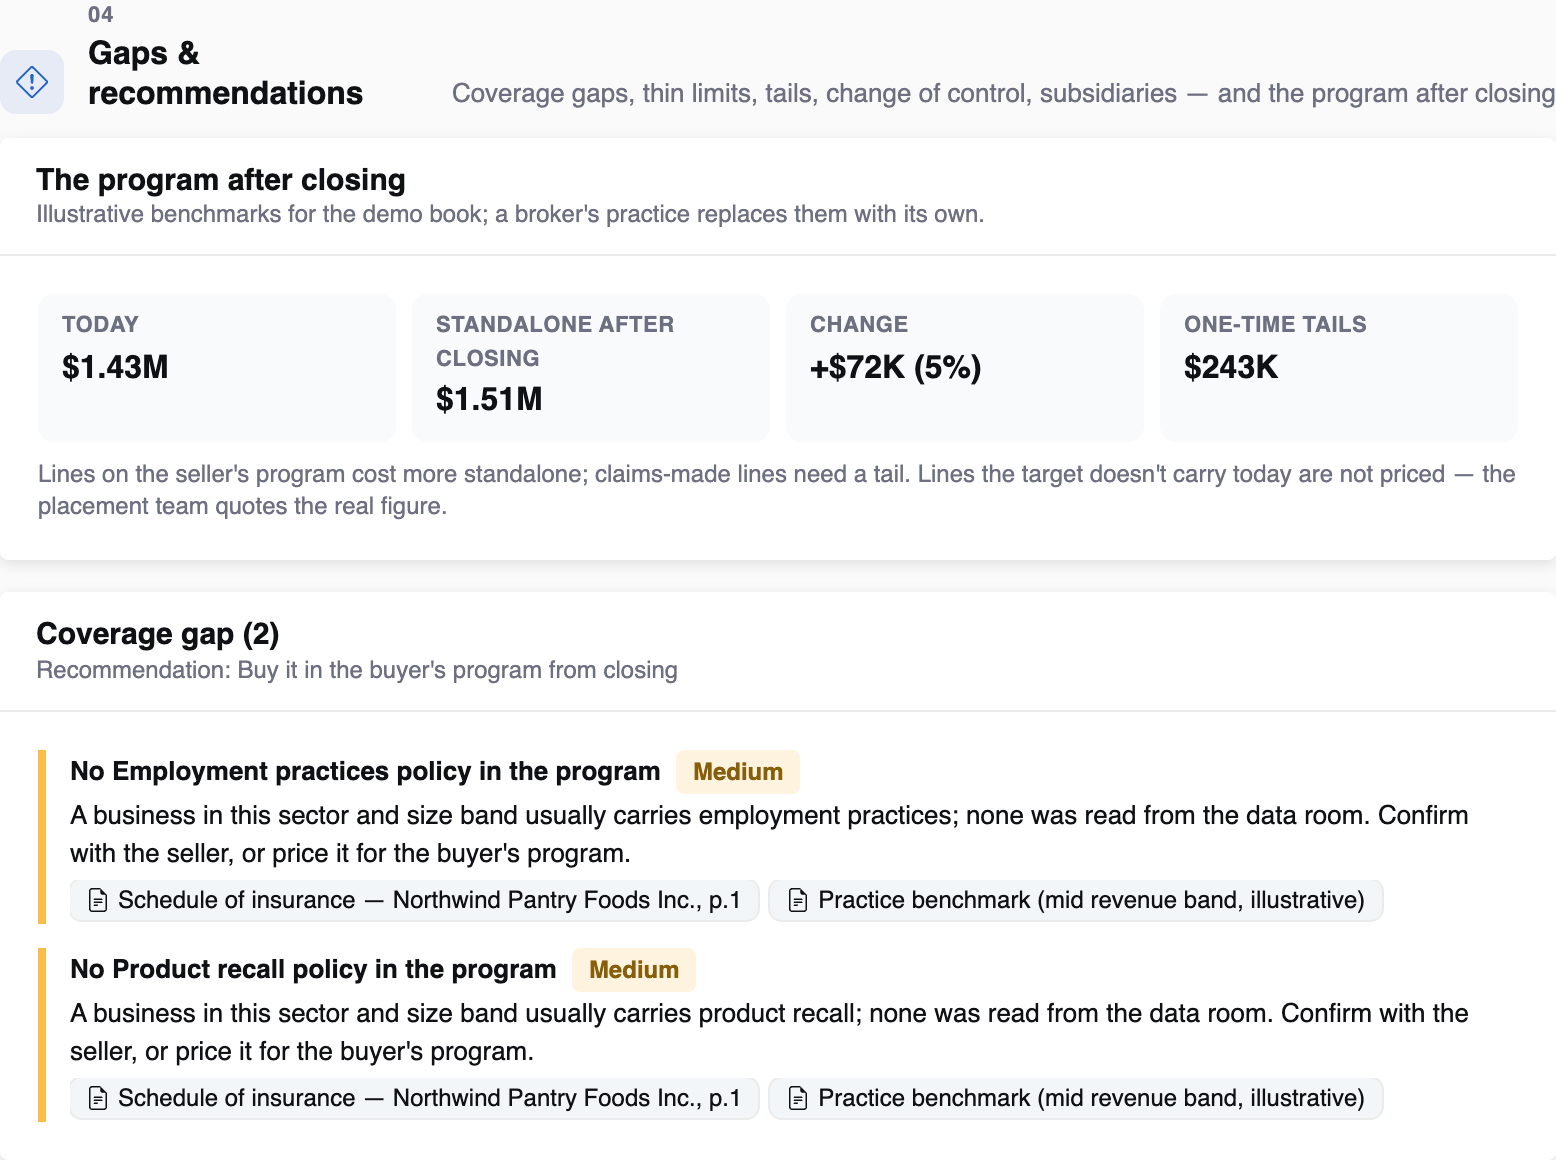
Eight lines, about $1.43M of premium; D&O and cyber claims-made; no recall and no EPL.
For a consumer products business the illustrative benchmark expects product recall and employment practices; both missing (medium).
18 claims over five years, about $1.17M incurred, with an open general liability claim for consumer illness after the recall.
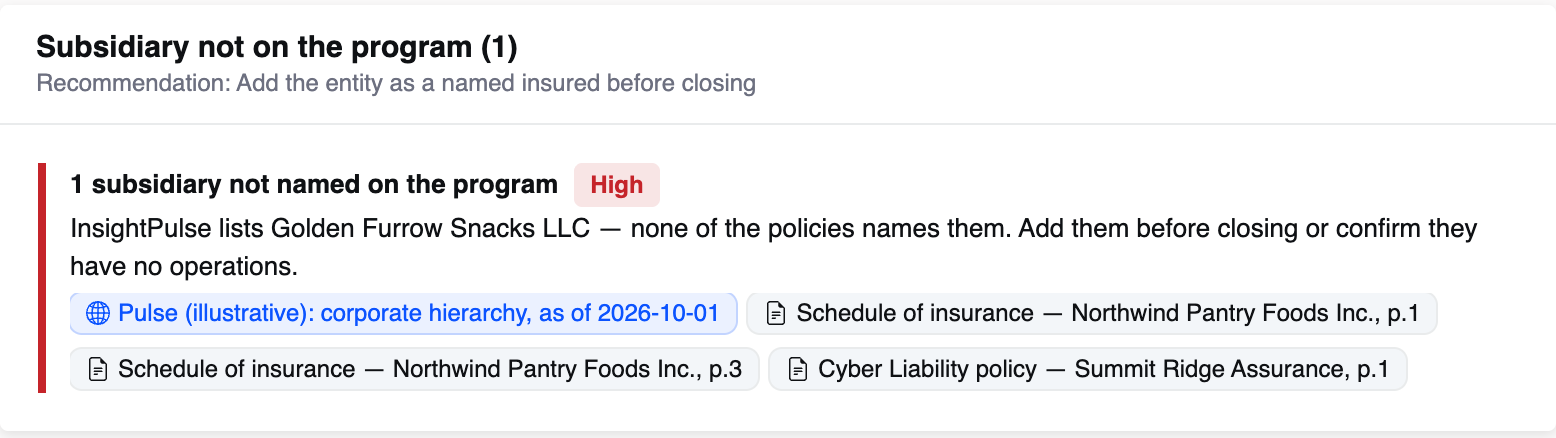
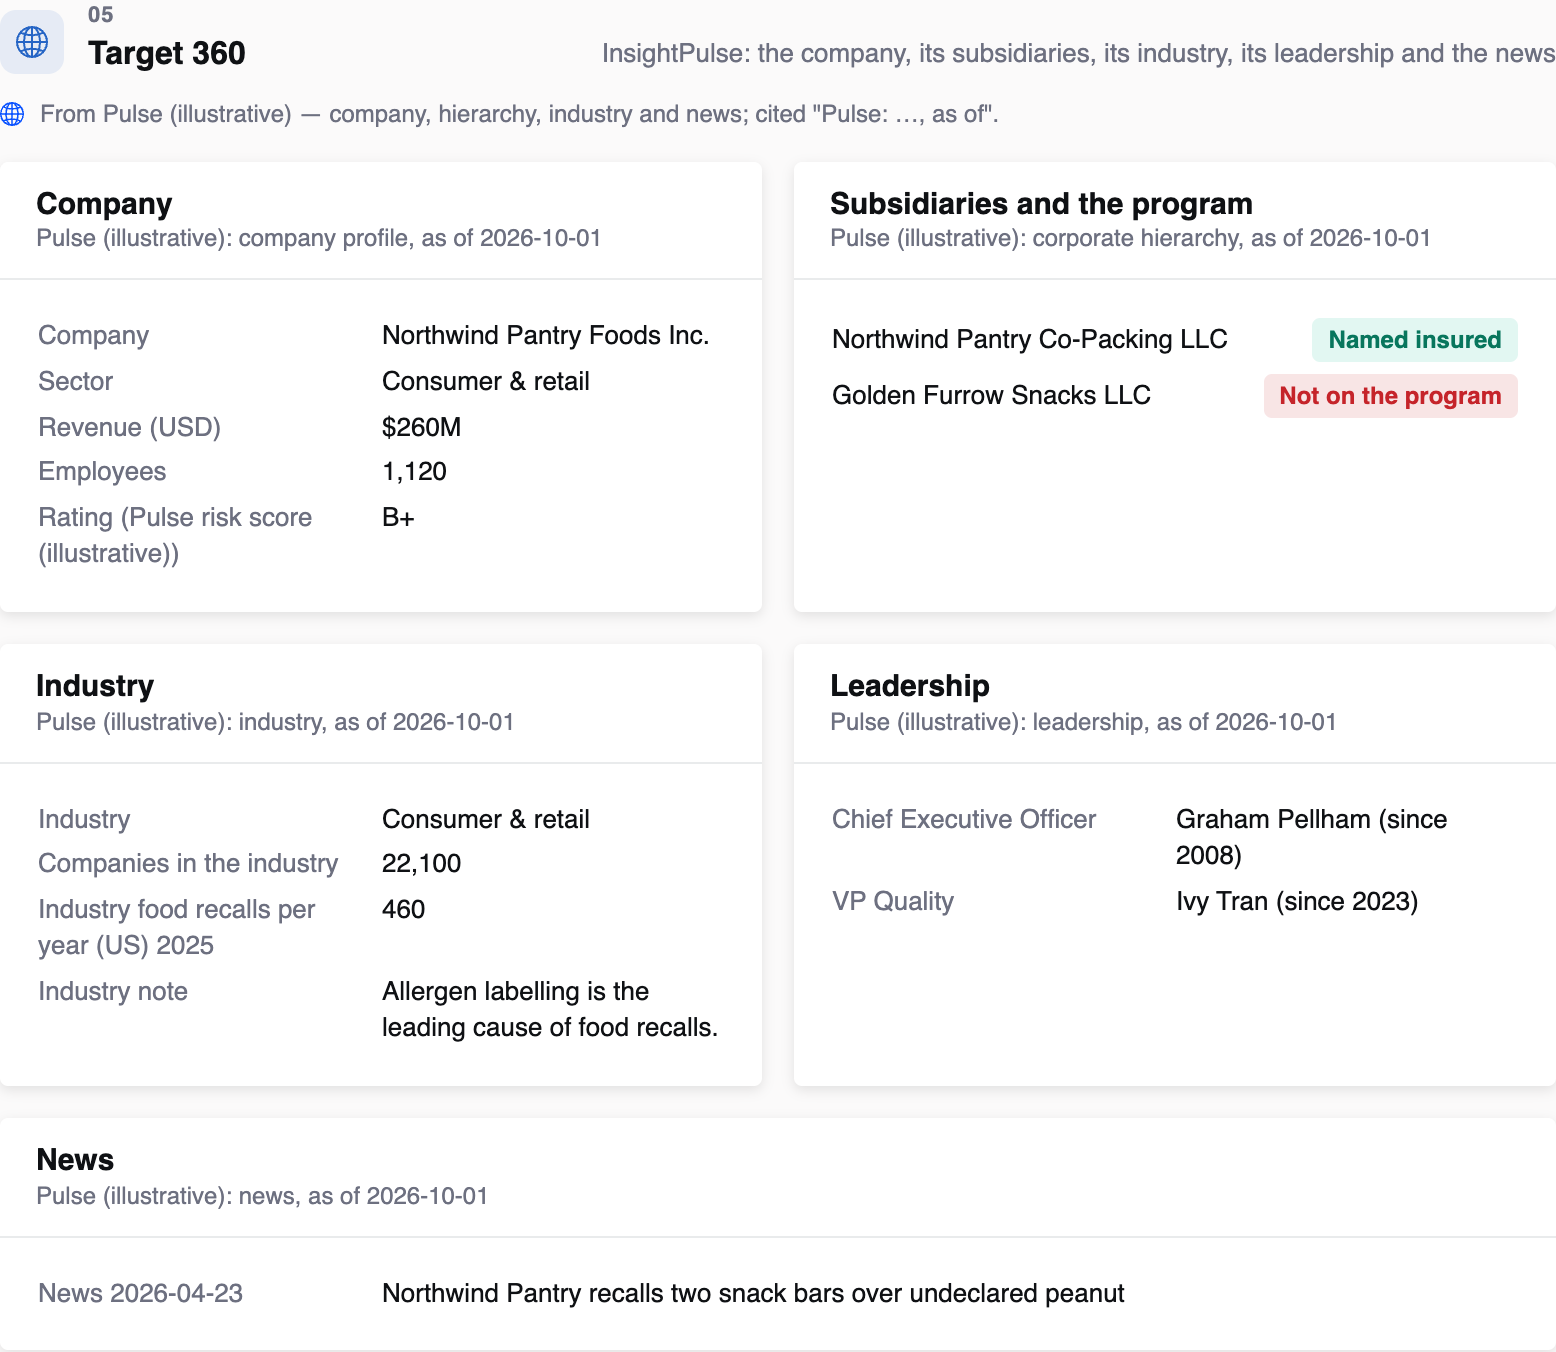
Golden Furrow Snacks LLC is in the corporate hierarchy; none of the policies names it (high).
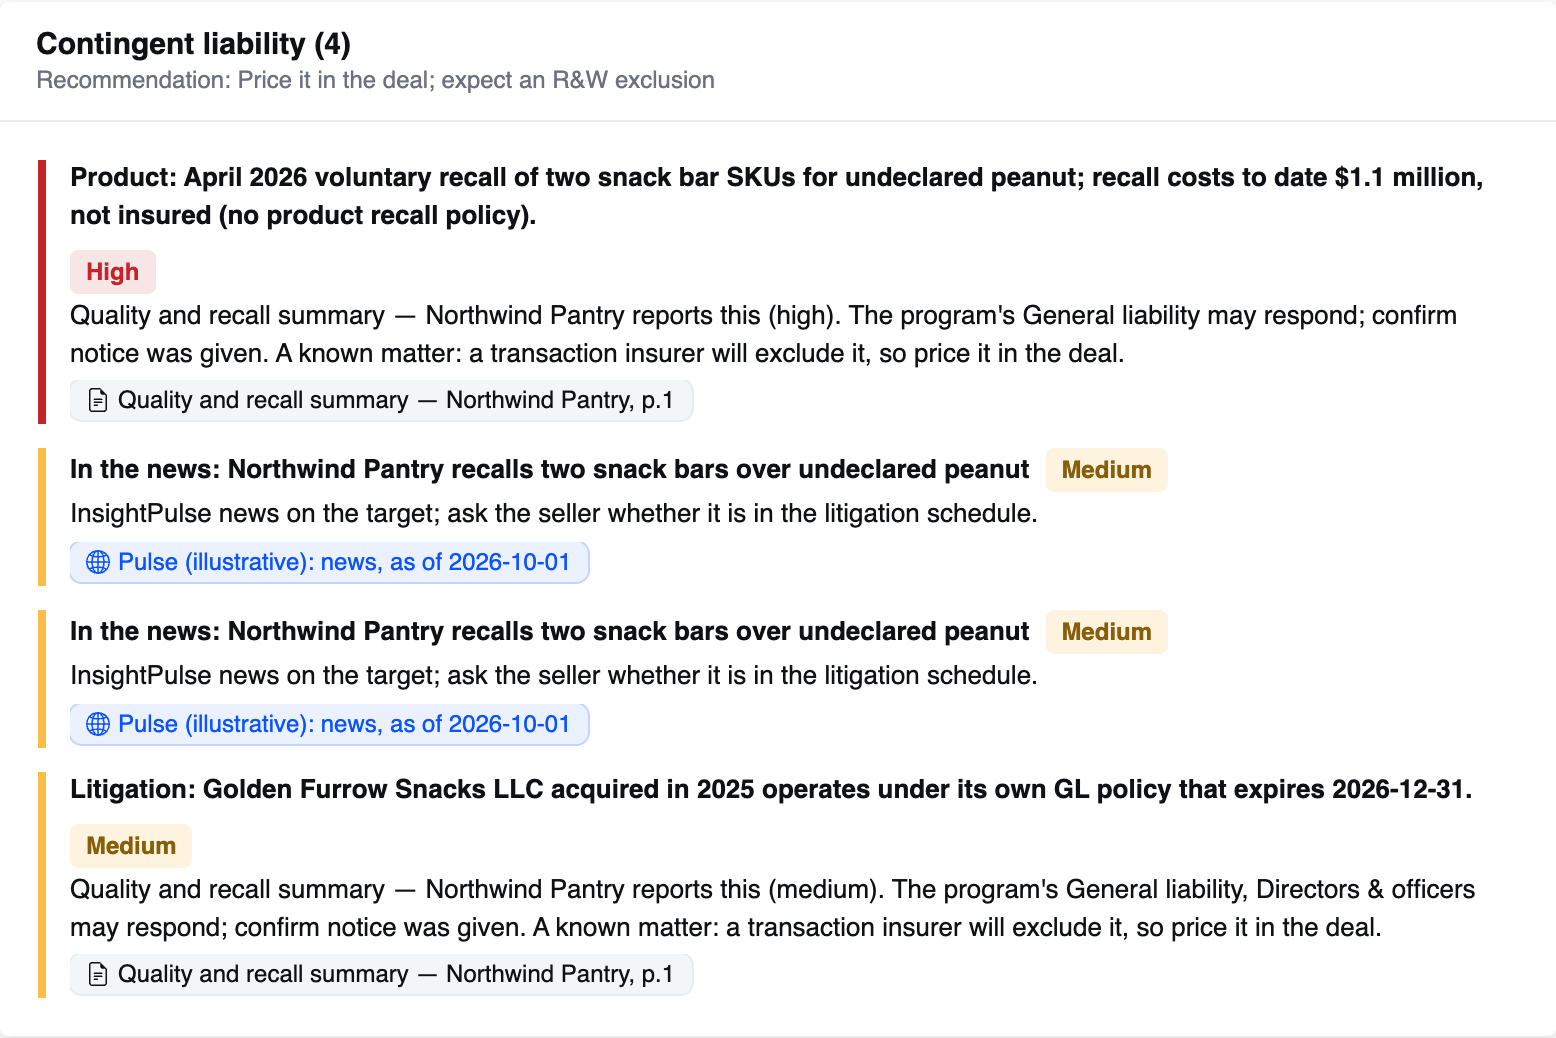
The recall’s $1.1M cost, not insured; the subsidiary on its own GL policy expiring at year end; the recall in the news, twice.
Cyber and D&O need tails; the sellers’ D&O needs a six-year run-off; the D&O converts to run-off at closing.
About $1.51M standalone after closing against $1.43M today (+5%), plus about $243K of tails.
Approves the recall and subsidiary findings as high; rejects the duplicate news item; marks the GL expiry for the closing checklist.
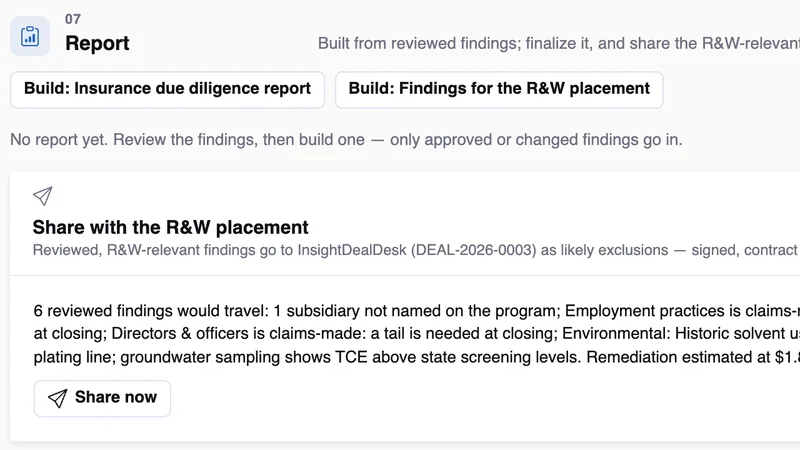
Shares the reviewed R&W-relevant findings with InsightDealDesk, where the recall lands as a likely exclusion.
The screens
How the subsidiary was found
| Agent | What it prepared | What it cites | Who decides |
|---|---|---|---|
| Coverage gap | No product recall policy; no employment practices policy | Schedule of insurance; benchmark (illustrative) | Broker |
| Subsidiary | Golden Furrow Snacks LLC not named on any policy | Pulse: corporate hierarchy; schedule; cyber declarations | Broker |
| Contingent liability | Recall costs $1.1M to date, not insured | Quality and recall summary, p.1 | Broker |
| Contingent liability | Subsidiary on its own GL policy expiring 2026-12-31 | Quality and recall summary, p.1 | Broker |
| Report | $1.43M today; $1.51M standalone; about $243K of tails | Cost engine | Broker |
Why the recall becomes an R&W exclusion
A recall the buyer knows about before signing is a known matter. The R&W underwriter will exclude it, so the price or a specific indemnity has to carry it. Shared from here, it reaches the placement team as a finding with its page, before the underwriting call.
Edge cases
| What happens | What InsightDueDiligence does |
|---|---|
| Pulse has no hierarchy for the target | The question is answered “not known to Pulse” and the finding asks the seller for an org chart; nothing is guessed. |
| The subsidiary has no operations | The broker changes the finding with the seller’s confirmation; the change is signed. |
| A finding is shared twice | InsightDealDesk is idempotent on each finding’s fingerprint; the second share lands nothing new. |
On the deal desk
The three findings that matter are connected on screen: the recall, the missing recall cover, and the subsidiary on its own expiring policy.
For IT & architecture
The subsidiary check is a join between Pulse’s hierarchy and the named insureds read from each policy, with both sides cited.
For practice leaders
An uninsured $1.1M loss and a 5% premium change: both belong in the investment committee paper, with their sources.
Questions we get asked
Does it price the recall policy?
No. Lines the target does not carry are not priced; the placement team quotes them.
Keep reading

Carving a business out of a global program
Every policy names the parent. On the day after closing, none of them will.
From diligence finding to R&W exclusion: the hand-off to InsightDealDesk
A reviewed finding travels, signed, and lands as a likely exclusion.